GoBD compared internationally
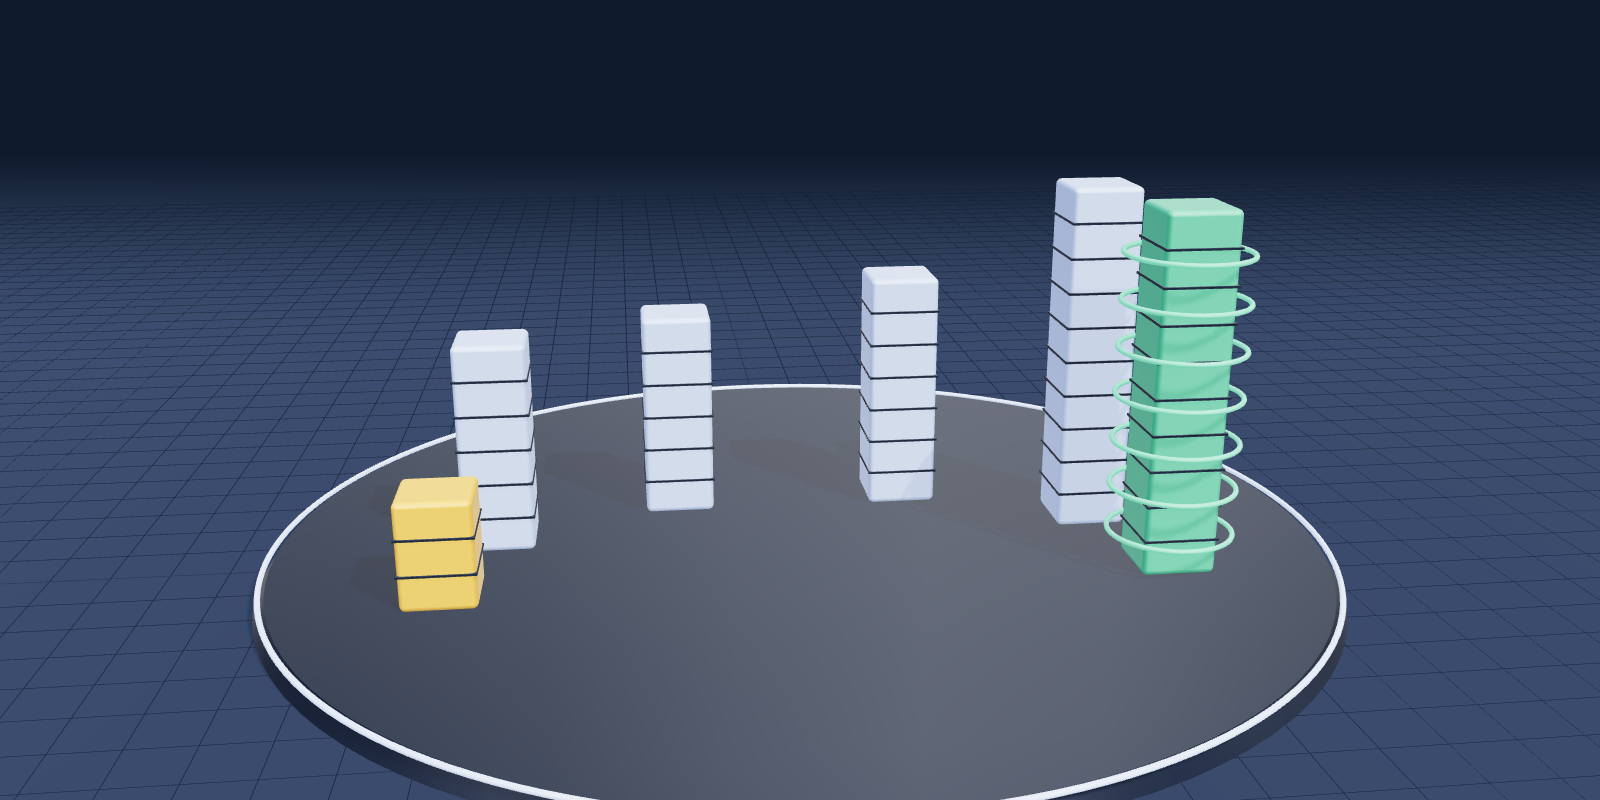
Short answer: most countries tell businesses how long to keep records. Germany's GoBD also tells them how: electronic records must stay complete, unaltered and traceable, stay machine-evaluable for a tax audit, and come with a written description of the process. The US and the UK set retention periods of roughly three to six years and, outside regulated sectors, say little about the form. Restow builds its archive for GoBD because we are based in Germany and our first customers are German businesses.
Side by side
| Jurisdiction | General retention for business records | What it says about electronic records |
|---|---|---|
| Germany (GoBD, AO, HGB) | 10 years for books and annual accounts, 8 years for accounting vouchers, 6 years for other documents such as commercial correspondence (§ 147 (3) AO, § 257 (4) HGB). | Detailed: completeness, correctness, timeliness, order, unalterability, traceability, machine evaluability, procedural documentation (GoBD). The tax auditor may access the data directly, have it evaluated to their specification or receive it in a machine-readable export (§ 147 (6) AO). |
| United States (IRS) | Generally 3 years; 6 years if income was under-reported by more than 25 %; 7 years for bad-debt or worthless-securities claims; employment tax records at least 4 years (IRS). | No general, GoBD-like rule on the form of electronic records for all businesses. |
| United States (SEC Rule 17a-4, broker-dealers only) | 6 years for certain core records, 3 years for others, including business communications. | Strict: either a complete time-stamped audit trail that allows re-creating any modified or deleted record, or a non-rewriteable, non-erasable format. |
| United Kingdom (HMRC, Companies Act 2006) | 6 years from the end of the financial year for company tax records (HMRC); VAT records at least 6 years; under company law 3 years for private and 6 years for public companies (s 388). | Records must be kept and produced on request; no GoBD-like catalogue of technical properties. |
| Switzerland (OR) | 10 years for business books and accounting vouchers (Art. 958f OR). | Electronic storage is allowed as long as the records match the underlying transactions and can be made readable at any time (Art. 958f (3) OR). |
| Austria (BAO) | 7 years for books, records and vouchers (§ 132 BAO). | Storage on data carriers is allowed if a complete, orderly and content-identical reproduction is guaranteed at any time until the retention period ends (§ 132 (2) BAO). |
General retention for business records
Periods from the table above. Only Germany also sets detailed rules on the form of electronic records for every business.
The bar shows the longest general period named for that jurisdiction, the text the full range; which one applies depends on the record. Not legal advice.
Why GoBD is an unusually high bar
- It regulates the form, not only the period. A record that is merely retained but could have been changed without a trace does not meet it. That is why an archive for GoBD needs integrity you can prove, for example a hash chain and storage-level immutability, not just a backup.
- It expects the process to be written down. The procedural documentation (Verfahrensdokumentation) describes how records are captured, stored and found again. Software can support it; writing it stays the business's job.
- The auditor works with your data. § 147 (6) AO lets the tax authority inspect the system, request evaluations or a machine-readable export. Printouts are not enough.
- The consequence is concrete. If the books or records cannot be relied on, the tax authority may estimate the tax base (§ 162 (2) AO).
- No certificate replaces it. There is no official GoBD certification of software; responsibility stays with the business. That is why Restow says "built for German GoBD requirements" and names the measures, never "certified".
Why Restow builds for GoBD
We are a small company in Bergisch Gladbach, Germany, and our first customers are German businesses and IT service providers, so German rules are the ones we have to get right first. Designing for the stricter rule set also gives everyone else useful properties: journaling as capture so nothing is missed, a hash chain so a change is detectable, object-lock storage so a record cannot be deleted early, retention and legal hold, and an export an auditor can check. What it does not give you is a compliance statement for another country; see the questions below.
The archive is in every edition since 0.1.0; journaling, enforced retention and legal hold are in Business and Service Provider. The current status is on the roadmap, the German details are in GoBD and email archiving, explained, and prices are on the pricing page.
Frequently asked
What is GoBD, in one sentence?
GoBD is the German Federal Ministry of Finance's administrative guidance (BMF letter of 28 November 2019) on how businesses must keep books, records and documents electronically so that the tax authority can rely on them: complete, correct, timely, orderly, unalterable, traceable and machine-evaluable, with procedural documentation.
I am in the US or the UK. Do I need GoBD?
Only if German tax law applies to you, for example through a German entity or a permanent establishment in Germany. Otherwise your own rules apply: in the US mainly IRS record-keeping and, for broker-dealers, SEC Rule 17a-4; in the UK, HMRC's six-year rule and the Companies Act. Ask your own tax advisor or counsel.
Is GoBD stricter than US or UK rules?
On retention it is longer than the general US and UK rules (up to ten years instead of three to six), and on the form of electronic records it is far more specific. The US has comparably strict technical rules only in regulated niches, most prominently SEC Rule 17a-4 for broker-dealers, which requires either a non-rewriteable, non-erasable format or a complete time-stamped audit trail.
Does an archive built for GoBD make me compliant elsewhere?
No. The technical properties GoBD asks for (integrity you can prove, completeness, retention, export for an auditor) are useful anywhere, but compliance depends on each country's rules and on how you operate the system. Restow does not claim compliance with SEC 17a-4, HMRC rules or any other regime.
Is the Restow archive available?
Yes, since 0.1.0. Every edition archives with a hash chain and full-text search; Business and Service Provider add journaling, enforced retention and legal hold. Backup and restore of Microsoft 365 and IMAP are in every edition.
Sources (read 2026-09-29)
- GoBD (BMF letter of 28 November 2019), amended by the BMF letters of 11 March 2024 and 14 July 2025, Federal Ministry of Finance
- § 147 AO, § 162 AO, § 257 HGB, gesetze-im-internet.de
- How long should I keep records?, IRS
- 17 CFR § 240.17a-4 and 18 U.S.C. § 1520 (audit workpapers of public-company auditors, 5 years), Cornell LII
- Company and accounting records and VAT Notice 700/21, GOV.UK; Companies Act 2006, s 388
- Swiss Code of Obligations, Art. 958f, fedlex.admin.ch
- § 132 BAO, RIS (Austria)